Stablecoins in the U.S. Explained: What the GENIUS Act Actually Changes for Your Money in 2026
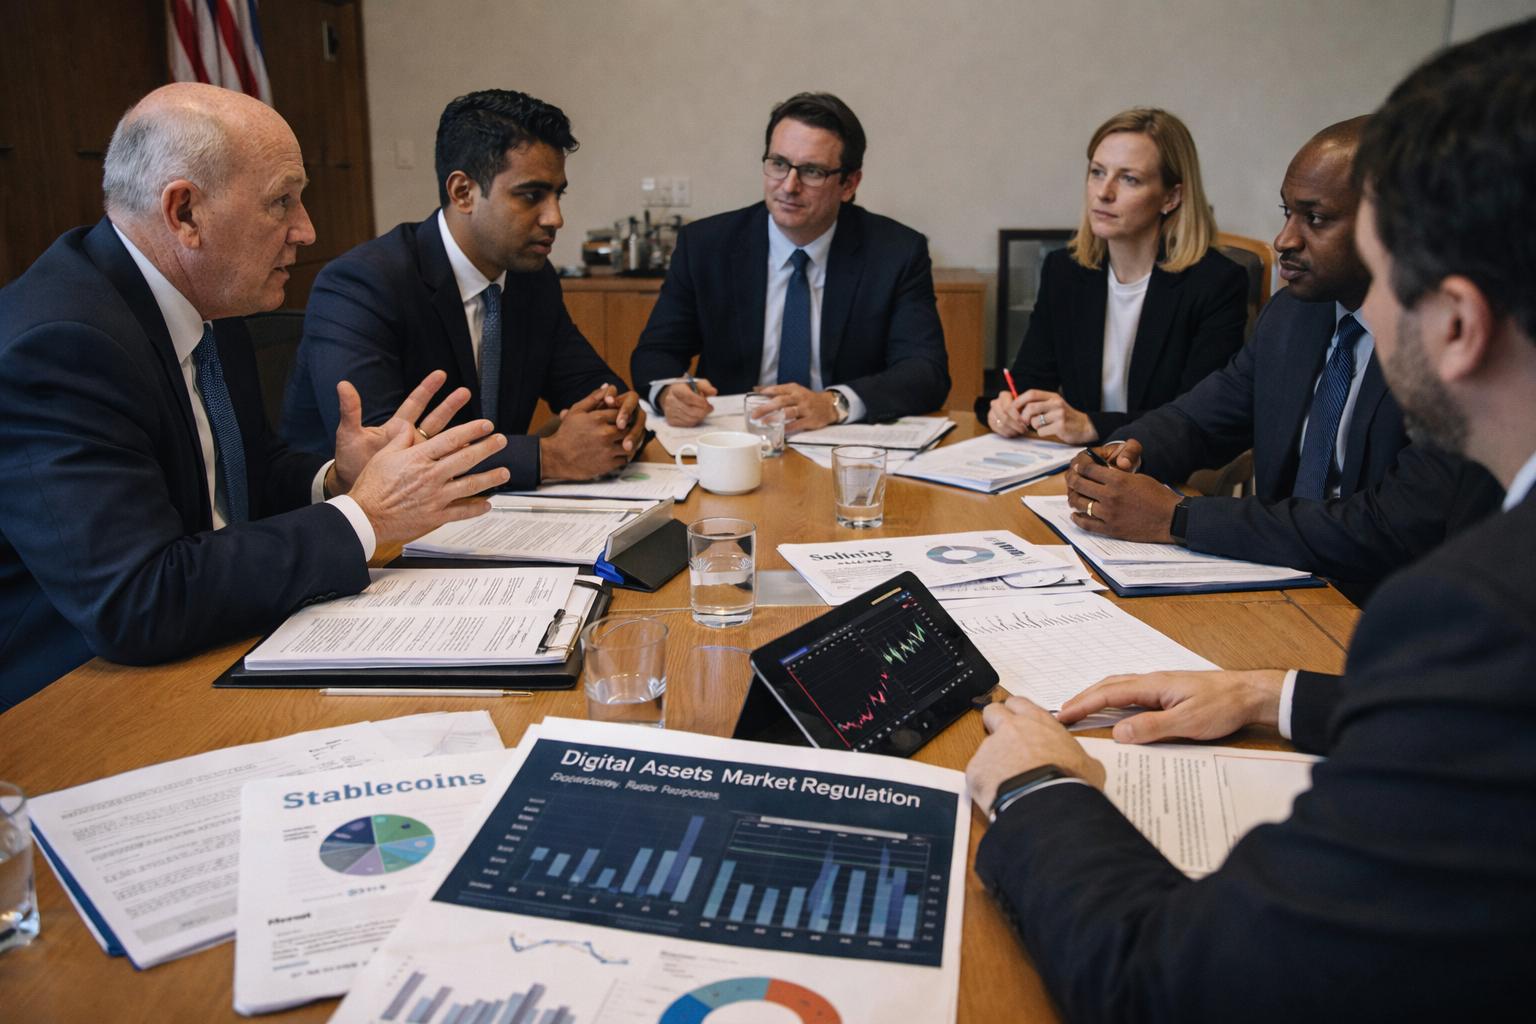
Stablecoins are digital tokens designed to maintain a stable value, usually by tracking the U.S. dollar. The GENIUS Act, signed into law in July 2025, creates a federal framework for payment stablecoins, including reserve, disclosure, redemption, licensing, and compliance requirements. For Americans, the law may improve transparency and confidence, but stablecoins remain different from insured bank deposits.
What Are Stablecoins, and Why Are Americans Paying Attention in 2026?Stablecoins have moved from a niche cryptocurrency concept toward something much closer to financial infrastructure. Unlike Bitcoin or other cryptocurrencies whose prices can fluctuate dramatically, a stablecoin is designed to maintain a relatively stable value. The most common model is a token intended to remain worth approximately one U.S. dollar.
That sounds simple, but the mechanics matter. A stablecoin is not automatically equivalent to a dollar sitting in your checking account. Its stability depends on the issuer, the assets backing the token, redemption arrangements, technology, and the rules governing the system around it.
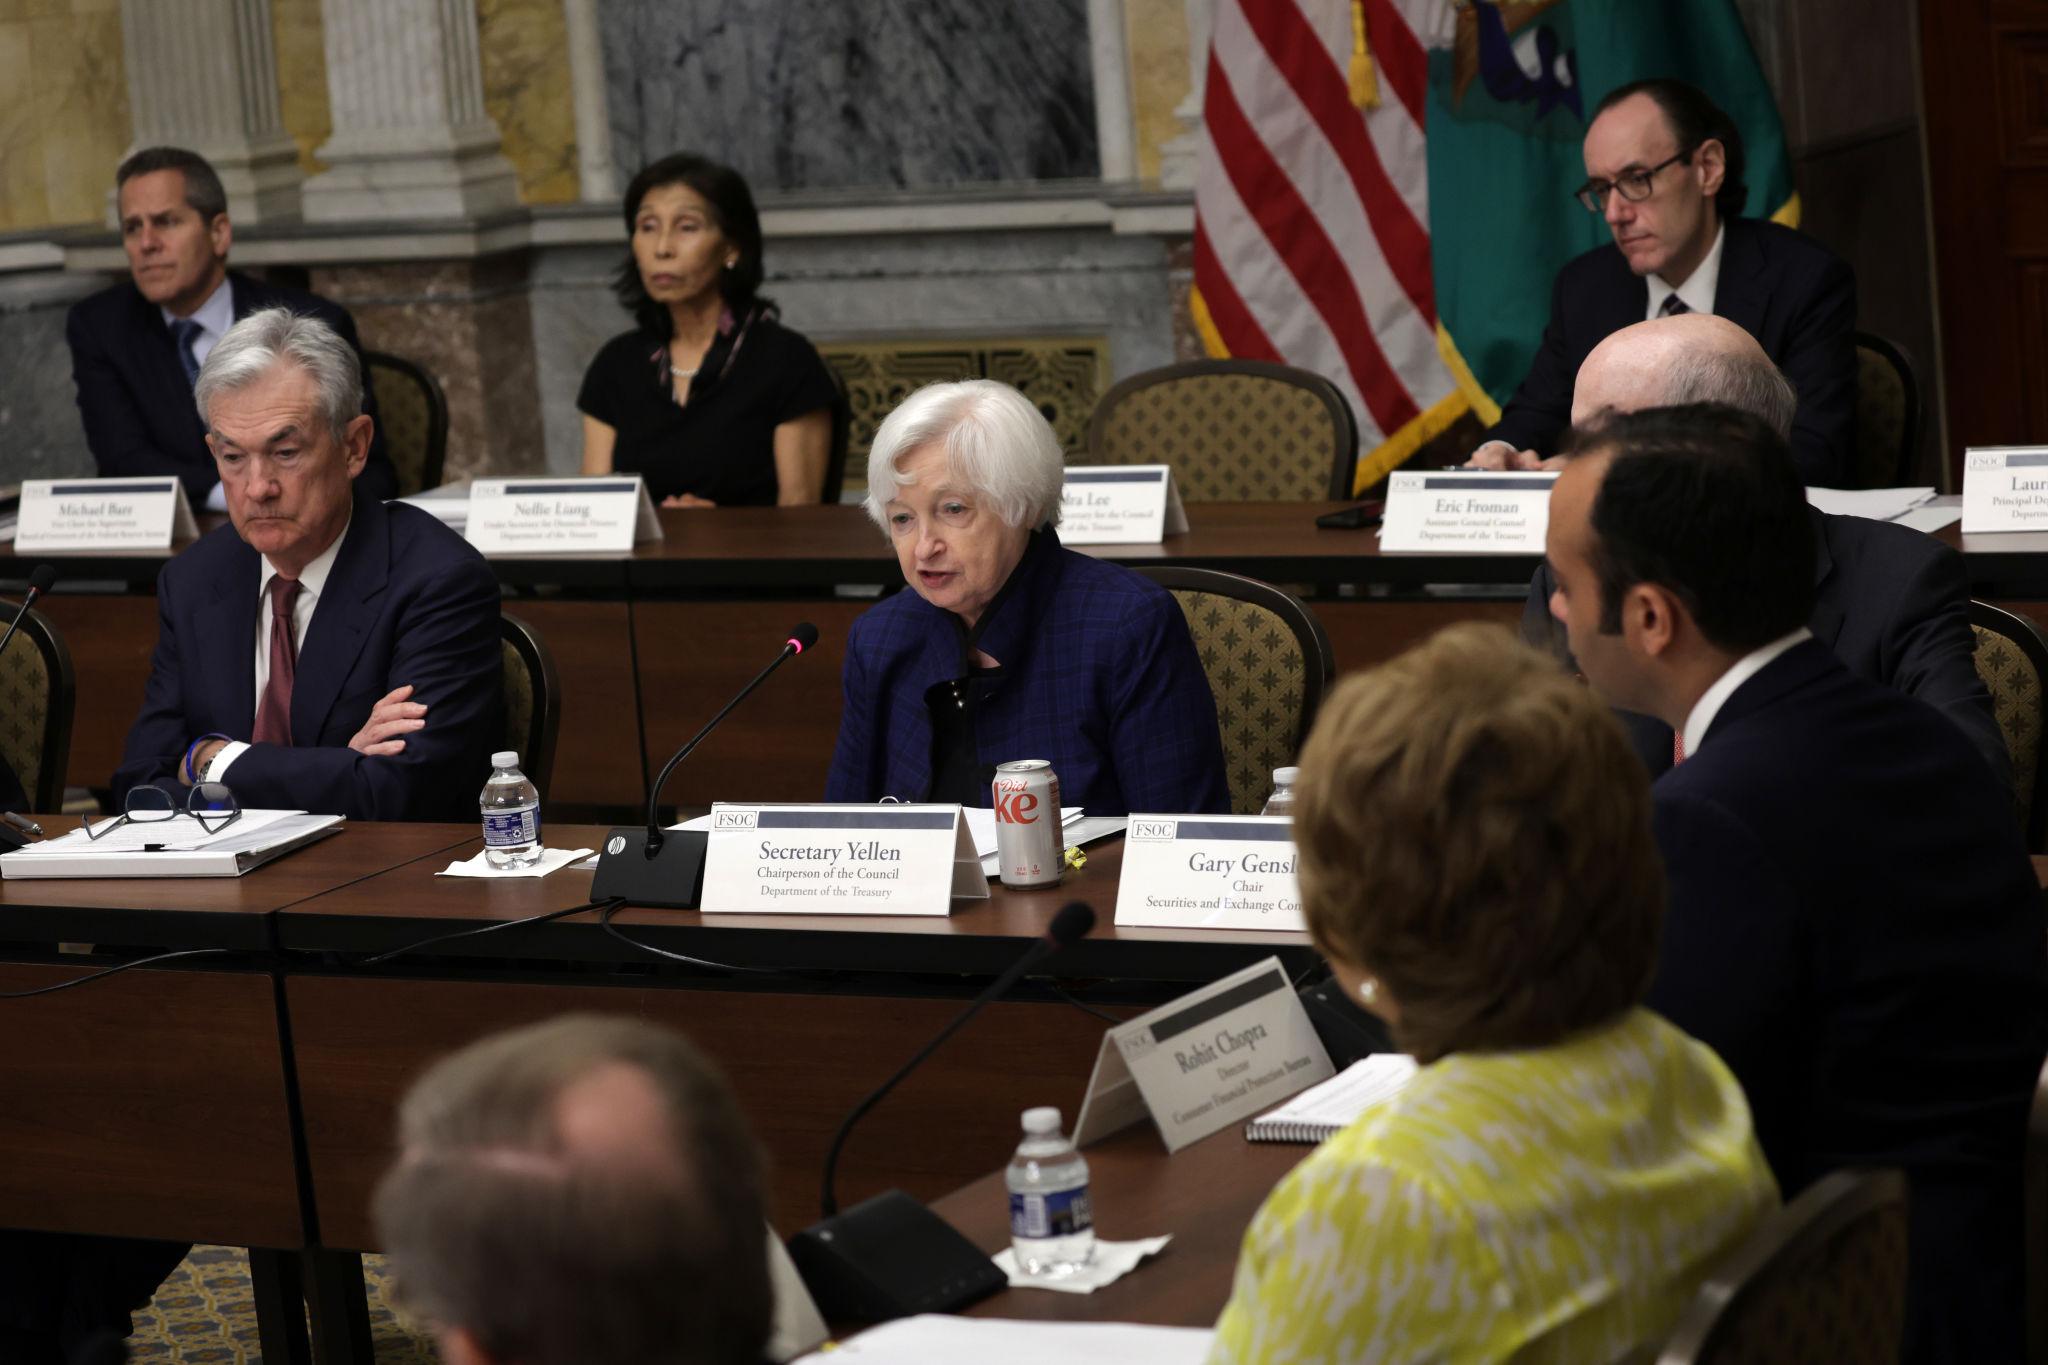
That distinction is particularly important in 2026 because the United States now has a federal legal framework specifically addressing payment stablecoins. President Donald Trump signed the Guiding and Establishing National Innovation for U.S. Stablecoins Act—the GENIUS Act—into law on July 18, 2025. Treasury and other federal regulators are now working through the detailed rules needed to put the statute into practice.
The Federal Reserve estimated that the stablecoin market had grown to roughly $300 billion by 2025, illustrating why policymakers increasingly view stablecoins as more than a speculative corner of crypto.
For an ordinary American, however, the key question is not whether stablecoins will become a multitrillion-dollar industry. It is much more practical:
What does the GENIUS Act actually mean if you own, receive, spend, or are considering using a stablecoin?
The answer is both more useful—and more limited—than some headlines suggest.
Stablecoins 101: How They Actually WorkA stablecoin is a blockchain-based digital asset designed to maintain a stable reference value. Dollar-denominated stablecoins attempt to stay close to $1.
Imagine that you purchase 1,000 units of a dollar-denominated payment stablecoin. Ideally, you should be able to use those tokens to transfer roughly $1,000 of value without worrying about the token behaving like Bitcoin and falling 20% overnight.
The issuer generally holds assets intended to support the outstanding tokens. Under the GENIUS Act framework, qualifying payment stablecoins must be backed on a one-to-one basis by specified permissible reserves rather than by a collection of risky investments.
The law's reserve approach is important because it addresses one of the biggest questions surrounding stablecoins:
What is actually behind the token?
The White House says the GENIUS Act requires 100% reserve backing with liquid assets such as U.S. dollars and short-term Treasury securities, along with monthly public disclosures concerning reserve composition.
That does not mean every cryptocurrency marketed as a stablecoin automatically receives the same treatment.
The GENIUS Act is specifically focused on payment stablecoins. The Federal Reserve has noted that the law does not cover every form of stablecoin, including certain crypto-backed and algorithmic models.
This is one of the most important distinctions for consumers.
A token can have the word "stable" in its marketing without necessarily being a permitted payment stablecoin under the new U.S. framework.
What Happens When Your AI Agent Gets Access to Your Email, Files and Apps? The New Security Problem Businesses Need to Understand
ChatGPT vs. Claude for Work: Which AI Is Actually Better for U.S. Businesses in 2026?
How Much Are U.S. Companies Really Spending on AI in 2026? The Numbers Behind the AI Spending Boom
Can AI Agents Actually Replace Business Software in 2026? What the “SaaSpocalypse” Debate Gets Right—and Wrong
The simplest way to understand the GENIUS Act is to think of it as a regulatory framework around the business of issuing payment stablecoins.
Before the law, the U.S. stablecoin market existed within a patchwork of federal and state laws, regulatory interpretations, enforcement actions, money-transmission rules, banking regulations, and cryptocurrency-specific requirements.
The GENIUS Act establishes a dedicated federal structure.
Among its major components are:
- Licensing and regulatory requirements for permitted issuers
- Reserve requirements
- Redemption requirements
- Disclosure and reporting obligations
- Consumer protection provisions
- Anti-money-laundering and sanctions requirements
- Rules affecting foreign-issued payment stablecoins
- Federal and state supervisory structures
The practical impact is that stablecoin issuance is moving closer to a regulated financial activity rather than remaining primarily a question of how an individual crypto company structures itself.
Treasury's 2026 implementation work demonstrates that this process is still unfolding. In August 2026, Treasury issued a proposed rule concerning the issuance, offering, and sale of payment stablecoins. Treasury said the Act is expected to become effective on January 18, 2027, with additional restrictions affecting the offering or sale of payment stablecoins to U.S. persons beginning later.
That timing matters.
The GENIUS Act was enacted in 2025, but 2026 is largely an implementation year.
💡 Discover More from IOT & Blockchain
AI & Automation
AI Agents vs. AI Assistants: What’s the Difference—and Which One Should Your Business Use in 2026?
AI & Automation
The Future of Generative AI in Creative Industries
AI & Automation
Machine Learning in Healthcare: Transforming Diagnosis and Treatment
AI & Automation
How Artificial Intelligence Is Redefining Workplace Productivity
No.
This is probably the single most important misconception consumers should avoid.
Suppose you have $10,000 in an FDIC-insured checking account at a participating bank. Deposit insurance can protect eligible deposits within applicable limits if the bank fails.
Now suppose you hold $10,000 worth of a stablecoin in a crypto wallet.
The fact that the token qualifies as a regulated payment stablecoin does not transform that wallet balance into an FDIC-insured bank deposit.
Stablecoins operate through a different legal and technological structure.
The GENIUS Act attempts to improve the quality and transparency of that structure, particularly by requiring permitted issuers to maintain appropriate reserves and meet regulatory obligations. But regulation is not the same thing as deposit insurance.
That distinction becomes especially important during financial stress.
If a stablecoin issuer encounters operational, legal, technological, or other problems, your experience can differ significantly from what happens with money held directly as an insured bank deposit.
The right way to think about the new framework is therefore:
The GENIUS Act is intended to make qualifying payment stablecoins more regulated and transparent—not identical to bank deposits.
Why Reserve Requirements Matter So MuchReserve backing is at the center of the GENIUS Act because stablecoins create a unique financial promise.
If an issuer has issued $20 billion of tokens that are supposed to remain redeemable for $20 billion, users need confidence that the issuer has assets capable of supporting that promise.
Consider a simplified example.
A hypothetical issuer creates 1 billion stablecoins. Each token is intended to represent $1. If the issuer holds approximately $1 billion in qualifying liquid reserves, it has a substantially different risk profile from an issuer that creates 1 billion tokens while holding only $600 million of assets.
The second structure creates a much larger redemption problem if users suddenly want their money back.
This is why the Federal Reserve has identified reserve and redemption rules as important elements of the GENIUS Act for mitigating run risk.
The reserve requirement also connects stablecoins to the U.S. Treasury market.
If issuers hold large quantities of short-term Treasury securities to support their tokens, growth in stablecoin circulation can translate into additional demand for those government securities. Treasury has emphasized this relationship in describing the legislation's potential effects.
For consumers, however, the key point is simpler:
Do not evaluate a stablecoin solely by its $1 price today. Evaluate how the issuer supports that $1 value.
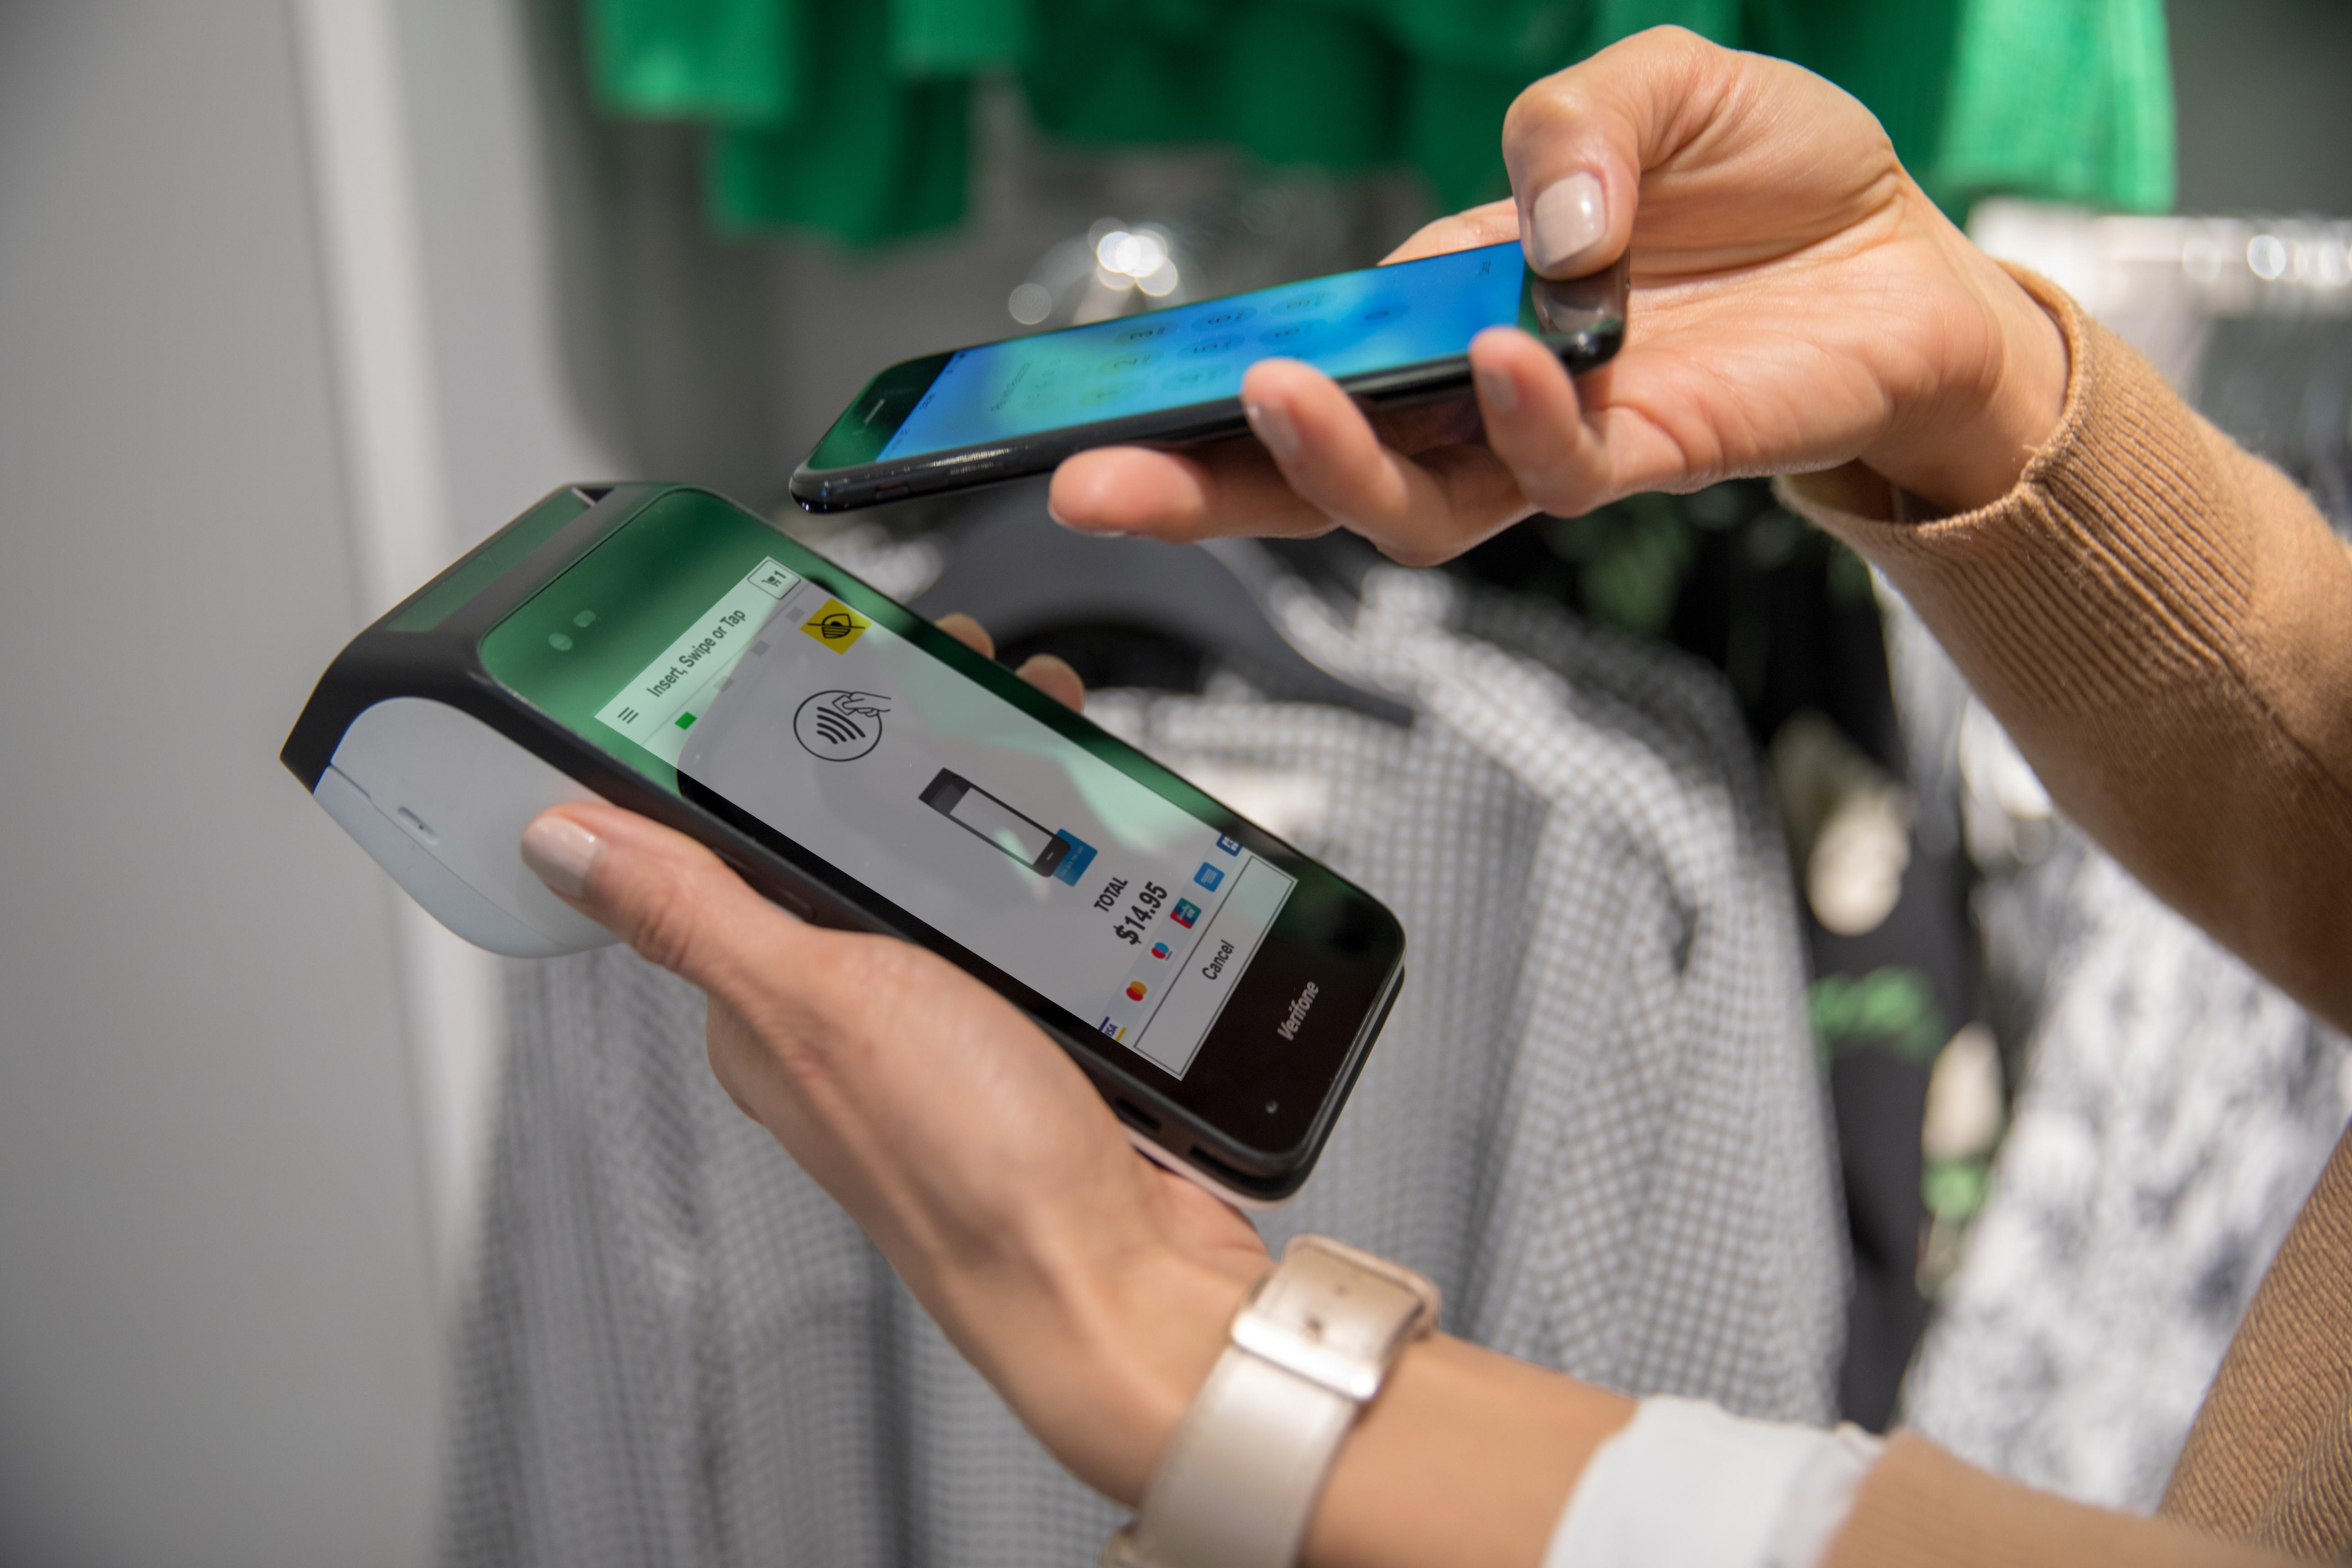 What Changes for Someone Who Uses Stablecoins to Send Money?
This is where the legislation could eventually become more noticeable in everyday life.
Imagine a small-business owner in Texas who needs to pay a contractor in another country. A traditional international transfer can involve banks, correspondent institutions, payment processors, currency conversion, cutoff times, and multiple fees.
A stablecoin transaction can potentially move dollar-denominated digital value across a blockchain without following exactly the same path.
The Federal Reserve has highlighted stablecoins as a potential alternative for cross-border payments and remittances, noting that transfers may be faster and lower-cost in some models.
But "potentially faster" does not mean "always cheaper."
The actual cost can depend on:
- Blockchain network fees
- Exchange or conversion spreads
- Wallet fees
- On-ramp and off-ramp charges
- Foreign-exchange costs
- Compliance requirements
- Whether the recipient can easily convert the stablecoin into local currency
So the GENIUS Act does not magically eliminate international payment costs.
What it does is establish a clearer regulatory framework around one of the financial instruments that could be used to deliver those payments.
Could Stablecoins Change How Americans Get Paid?Possibly, although this is likely to develop gradually.
Today, most Americans are paid through conventional banking infrastructure. Employers generally use direct deposit, payroll providers, ACH transfers, checks, or similar systems.
Stablecoins introduce another possibility: digital-dollar payments that can move through blockchain networks.
Consider a freelance designer who works with a U.S. company and an international client. A stablecoin could theoretically provide a common dollar-denominated settlement asset without requiring both parties to use exactly the same banking rails.
However, regulatory compliance and tax reporting still matter.
Receiving a stablecoin is not automatically equivalent to receiving "free money" outside the financial system. Tax treatment can depend on the transaction and how the asset is used, and users should keep appropriate records.
The GENIUS Act primarily addresses stablecoin regulation. It does not erase the broader tax rules that apply to cryptocurrency and digital assets.
For someone accustomed to the relative openness of certain cryptocurrency networks, this can feel like a major change.
But from a regulatory perspective, it is intentional.
The U.S. government is trying to make stablecoins usable as financial infrastructure without creating a parallel payment system outside anti-money-laundering and sanctions controls.
What Does the GENIUS Act Mean for Stablecoin Issuers?For issuers, the changes are considerably more consequential.
The law establishes requirements concerning who can issue permitted payment stablecoins and how those issuers must operate.
Treasury's 2026 rulemaking shows that regulators are defining exactly when an entity is considered to be issuing a payment stablecoin in the United States and when a stablecoin may be offered or sold to people in the country.
The law also creates a distinction between federal and state regulatory pathways.
Treasury's April 2026 proposal explains that issuers with no more than $10 billion in consolidated outstanding stablecoin issuance may qualify for a state-level regulatory regime if that regime is substantially similar to the federal framework.
For large financial companies, the regulatory consequences could therefore be substantial.
For smaller issuers, the question becomes whether compliance costs make the stablecoin business economically viable.
For consumers, these changes could eventually influence which stablecoins remain widely available through U.S. platforms.
Why Anti-Money-Laundering Rules Matter to Everyday UsersSome people see compliance rules as something that only affects financial institutions.
In practice, they can directly affect consumers.
Treasury's Financial Crimes Enforcement Network and Office of Foreign Assets Control proposed rules in April 2026 addressing anti-money-laundering and sanctions-compliance requirements for permitted payment stablecoin issuers. The proposal would treat permitted issuers as financial institutions for relevant Bank Secrecy Act purposes and require effective sanctions-compliance programs.
That means users should expect regulated stablecoin services to behave more like mainstream financial platforms in certain respects.
You may encounter:
- Identity verification
- Transaction monitoring
- Sanctions screening
- Account restrictions
- Recordkeeping
- Compliance-related transaction reviews
For someone accustomed to the relative openness of certain cryptocurrency networks, this can feel like a major change.
But from a regulatory perspective, it is intentional.
The U.S. government is trying to make stablecoins usable as financial infrastructure without creating a parallel payment system outside anti-money-laundering and sanctions controls.
Will Stablecoin Transactions Become More Private?Not necessarily.
Blockchain transactions can create a permanent public record of transfers, depending on the blockchain being used.
At the same time, regulated intermediaries can be required to identify customers and monitor transactions.
That creates a different privacy model from cash.
Cash transactions can occur without a blockchain ledger identifying every transfer. Public blockchains can make transaction histories observable, while centralized issuers and exchanges may hold additional customer information.
Therefore, Americans should not assume that stablecoins are inherently anonymous.
In fact, the direction of U.S. regulation points toward stronger compliance expectations for permitted issuers.
 Can Stablecoins Earn Interest?
This is another area where consumers need to distinguish between a payment stablecoin and other financial products.
A stablecoin itself is generally designed to maintain value, not function as a savings account.
An issuer may earn income from the assets backing the tokens. But that does not automatically mean the holder of the stablecoin receives the underlying interest.
This difference is easy to overlook.
Suppose an issuer holds Treasury securities supporting a stablecoin. Those Treasury securities can generate interest for the issuer. That does not necessarily mean a person holding $5,000 in the stablecoin receives Treasury interest.
Some platforms may offer rewards or yield-like products, but those arrangements need to be evaluated separately.
Consumers should ask:
Who receives the yield generated by the reserves?
That question can reveal a major difference between competing digital-dollar products.
What Happens if a Stablecoin Falls Below $1?A stablecoin is designed to maintain a stable value, but "stable" does not mean mathematically guaranteed to trade at exactly $1 every second.
Market conditions, liquidity, trading venues, transaction demand, technical problems, and confidence in the issuer can affect the market price.
For example, imagine a stablecoin temporarily trades at $0.99 on an exchange.
If users can reliably redeem the token for $1 under the issuer's applicable redemption process, arbitrage and redemption mechanisms may help restore the market price toward its intended value.
But the existence of a legal framework does not mean every market price deviation disappears instantly.
This is why redemption rules are so important.
The Federal Reserve has specifically connected the GENIUS Act's reserve and redemption requirements with efforts to reduce run risk.
Does the GENIUS Act Protect You From Crypto Scams?No.
This is another area where expectations should remain realistic.
The law regulates qualifying payment stablecoin issuers. It does not guarantee that every website, app, wallet, token, social-media account, or investment opportunity involving the word "stablecoin" is legitimate.
A scammer can still impersonate a legitimate company.
A user can still send funds to the wrong blockchain address.
A compromised wallet can still be drained.
A fraudulent website can still steal login credentials.
A token can still be unrelated to the regulated payment stablecoin framework.
The safest approach is to distinguish regulation of an issuer from safety of every activity surrounding the asset.
Consumers should independently verify the issuer, platform, wallet address, transaction destination, and terms of service before moving meaningful amounts of money.
What Should Americans Check Before Using a Stablecoin?The arrival of the GENIUS Act makes due diligence more important, not less.
If you are considering stablecoins for payments or digital-asset transactions, start with the fundamentals.
- Check the issuer
Find out who actually creates the token and what regulatory status applies to that issuer.
- Understand the reserves
Look for clear information about what supports the token and how frequently reserve information is disclosed.
- Understand redemption
Ask how a holder converts the token back into U.S. dollars and whether redemption is available directly or only through an intermediary.
- Check the platform
A regulated stablecoin does not mean every exchange or wallet offering it has identical protections.
- Understand fees
Look at conversion spreads, network fees, withdrawal costs, and any platform charges.
- Keep records
Maintain records of purchases, sales, transfers, conversions, and payments for tax and accounting purposes.
- Start small
If you are unfamiliar with blockchain transactions, a small test transfer can help identify operational problems before you move a larger amount.
A Real-World Example: A $2,000 PaymentConsider Sarah, a small-business owner in California.
She needs to pay a contractor $2,000. Her existing payment method takes several business days and costs a fee.
Sarah uses a permitted payment stablecoin through a regulated service.
The transaction may be processed quickly because the stablecoin moves on a blockchain network rather than through the exact same settlement process as a conventional bank transfer.
But Sarah still has several considerations.
She needs to acquire the stablecoin, pay any applicable fees, ensure the contractor provides the correct wallet address, and eventually account for the transaction properly.
The GENIUS Act may give Sarah more confidence that the stablecoin issuer operates under defined reserve and compliance rules.
It does not guarantee that her transaction is free, instant, irreversible without risk, or immune to fraud.
That's the realistic value proposition.
A Second Example: Why Reserve Transparency MattersNow consider David, who holds $25,000 in a stablecoin because he wants to move funds between crypto platforms.
He sees that the token consistently trades around $1.
Before the GENIUS Act, he might have had to conduct his own research into the issuer's reserve practices and legal structure.
Under the emerging regulatory framework, permitted issuers face more formal reserve and disclosure obligations.
That can improve the information available to David.
But he still needs to understand what he owns.
His $25,000 stablecoin balance is not automatically:
- An FDIC-insured deposit
- A Treasury security held directly in his name
- A traditional money-market fund
- A guarantee against every type of loss
Regulatory clarity can reduce certain risks while leaving others intact.
How the GENIUS Act Could Affect BanksBanks are likely to be important participants in the stablecoin ecosystem.
The law creates opportunities for regulated financial institutions and other permitted entities to participate in digital payment infrastructure while imposing new regulatory responsibilities.
The Federal Reserve has also been working on related regulatory questions during 2026. For example, the Board has participated in proposed rules concerning customer-identification requirements for permitted payment stablecoin issuers.
For banks, stablecoins could represent both competition and infrastructure.
A bank could potentially face competition from nonbank digital-dollar issuers while also providing custody, settlement, liquidity, banking, and other services to the stablecoin industry.
That makes the eventual structure of the market difficult to predict.
The more useful conclusion is that the GENIUS Act brings stablecoins closer to the regulated financial system rather than creating a completely separate financial universe.
Could Stablecoins Strengthen the U.S. Dollar?Potentially.
Dollar-denominated stablecoins already extend digital access to U.S. dollar value around the world.
If stablecoins grow substantially, they could increase international demand for dollar-denominated assets and reinforce the role of the dollar in digital commerce.
The Treasury Department has explicitly argued that stablecoin growth could increase demand for U.S. Treasury securities and support the dollar's global role.
But that is a policy and market outcome, not a guaranteed result.
Foreign users can adopt stablecoins for convenience without necessarily changing their broader currency preferences. Other countries may also develop competing digital payment systems.
The long-term outcome will depend on adoption, regulation, interest rates, technology, international policy, and consumer behavior.
What the GENIUS Act Does Not ChangeIt is useful to separate what the law changes from what it does not.
The GENIUS Act does not:
- Turn stablecoins into FDIC-insured deposits
- Guarantee that every stablecoin stays exactly at $1
- Eliminate cryptocurrency scams
- Make blockchain transactions reversible
- Remove tax responsibilities
- Make every crypto wallet regulated
- Regulate every type of stablecoin
- Guarantee that every stablecoin transaction is free
- Eliminate technology and cybersecurity risks
This distinction is essential because regulatory headlines can create a false impression that crypto risk has disappeared.
It has not.
The risk profile is simply becoming more clearly defined for the specific category of payment stablecoins covered by the law.
What Changes for Consumers During 2026?For many Americans, the most important point is that 2026 is not necessarily the year when every consumer suddenly notices a completely different stablecoin market.
Instead, this is the year in which regulators are turning the law into operational rules.
Treasury issued proposed rules in April and August 2026, while federal regulators have separately proposed rules concerning customer identification and other implementation issues.
That means platforms, issuers, banks, fintech companies, and other participants are working through questions about compliance, licensing, reporting, reserves, foreign issuers, and consumer access.
For consumers, that could eventually lead to more standardized disclosures and clearer distinctions between regulated payment stablecoins and other crypto assets.
It may also lead to some products becoming less available in the U.S. if their issuers or distributors do not meet the new requirements.
When Does the GENIUS Act Take Effect?The law was signed on July 18, 2025, but its implementation occurs in stages.
Treasury's August 2026 proposed rule states that the expected effective date is January 18, 2027. It also describes later restrictions affecting the ability of digital-asset service providers to offer or sell payment stablecoins to people in the United States.
That means a headline saying "stablecoins are now regulated" needs some context.
The law exists.
The regulatory framework is being built.
And the practical obligations are being phased into effect.
Consumers should therefore expect the stablecoin market to continue changing throughout 2026 and into 2027.
The most important consequence of the GENIUS Act may not be that Americans suddenly start paying for groceries with stablecoins.
The more significant change may happen behind the scenes.
Banks, fintech companies, payment processors, marketplaces, businesses, and financial institutions can now build around a clearer legal framework for dollar-denominated blockchain payments. That could gradually influence how money moves across borders, how businesses settle transactions, and how digital commerce handles dollars.
For consumers, the appropriate response is neither enthusiasm nor fear.
It is understanding.
A qualifying payment stablecoin is becoming a more regulated financial instrument, but it remains different from cash in a bank account. Reserve requirements can improve the foundation supporting the token. Disclosure rules can improve transparency. Licensing and compliance requirements can make the ecosystem more accountable.
None of those changes removes the need to understand what you own.
The biggest practical lesson for 2026 is therefore straightforward: regulation can make stablecoins more credible without making them identical to traditional money.
As the remaining GENIUS Act rules take shape, Americans should pay particular attention to issuer status, reserve disclosures, redemption rights, platform protections, fees, and the difference between payment stablecoins and other crypto assets.
That is where the law's real-world impact will ultimately be measured—not by the size of the headlines, but by whether digital dollars become a genuinely useful, transparent, and dependable part of the American payments system.
Stay in the Loop

You May Also Like
 AI & Automation 7 min read| 01 Sep 2026
The Impact of Deep Learning on Natural Language Processing (NLP)
Deep learning has revolutionized the field of Natural Language Processing (NLP), leading to remarkable advancements in how machines understand and generate human language. By leveraging complex neural networks and large datasets, deep learning algorithms have transformed NLP applications, enhancing their accuracy and capabilities.
 IOT & Blockchain 4 min read| 15 Aug 2026
From Fans to Funders: Blockchain Revolutionizes Fan Engagement
Blockchain technology transforms fan engagement by offering new ways for fans to support, interact with, and invest in their favorite artists and creators.
 AI & Automation 2 min read| 27 Jun 2026
AI in Agriculture: Improving Crop Yield and Sustainability
Artificial intelligence (AI) is revolutionizing agriculture by providing innovative solutions to improve crop yield, optimize resource management, and promote sustainability. From precision farming to crop monitoring, AI technologies offer farmers valuable insights and tools to enhance productivity and efficiency in agricultural practices.
 AI & Automation 3 min read| 20 Aug 2026
Machine Learning in Cybersecurity: Protecting Data in a Digital World
Machine learning is becoming a crucial tool in the field of cybersecurity, enhancing the ability to detect, prevent, and respond to cyber threats. As cyberattacks become more sophisticated, machine learning algorithms are playing a pivotal role in safeguarding data and maintaining digital security.